The Perpetual Student Loophole: How to Use a 529 Plan to Fund Your Rent and Living Expenses in Retirement
From Simple Investing · 14 articles · latest
Conventional retirement planning adheres to an almost dogmatic script: pay off a thirty-year suburban mortgage by your mid-sixties, downsize into a quiet condo, and carefully meter out taxable distributions from a Traditional 401(k) while obsessing over tax brackets. But for modern retirees who prize geographic mobility, prefer renting in walkable cultural hubs, or want to monetize their household utility and grocery bills while staying intellectually engaged, there is an extraordinary tax loophole hiding in plain sight: The Perpetual Student Strategy.
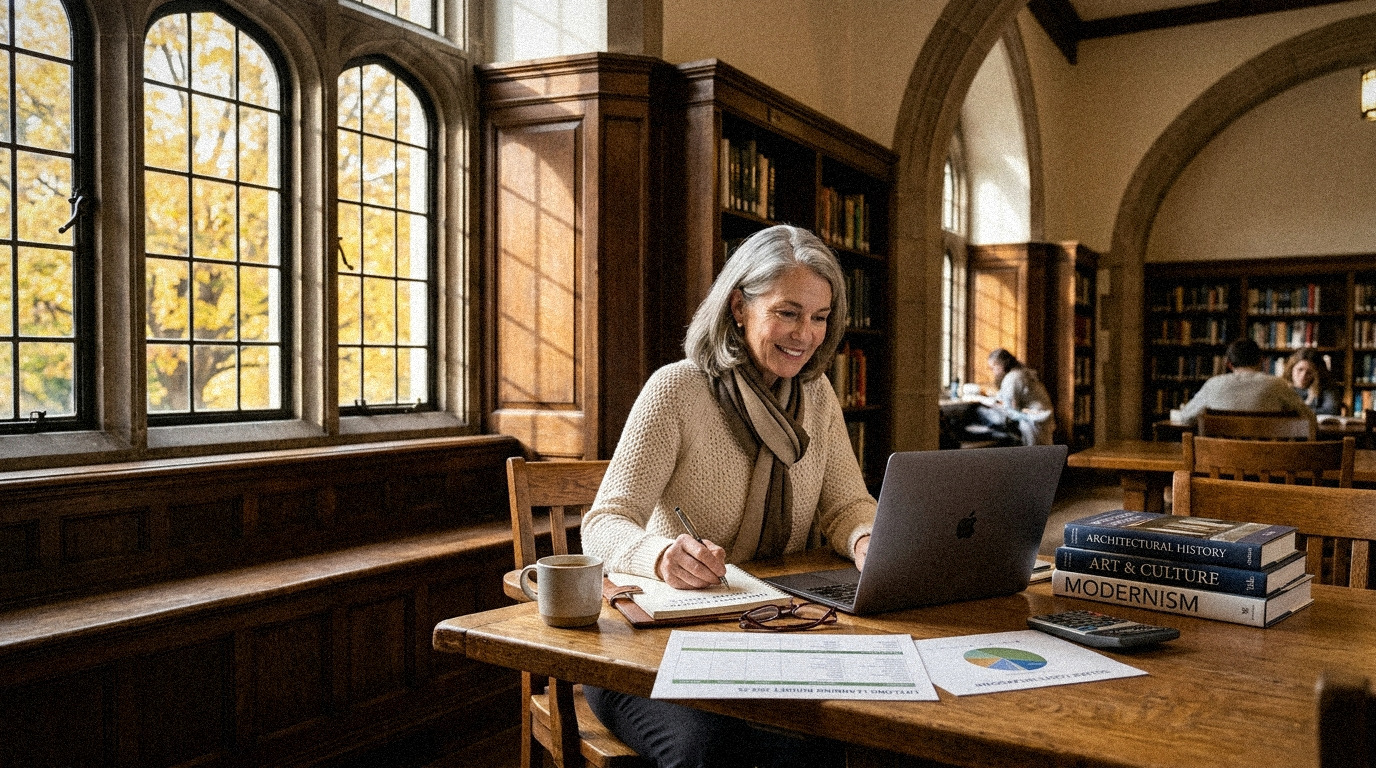
Most investors mistakenly assume Section 529 qualified tuition plans are exclusively reserved for teenagers pursuing four-year undergraduate degrees. In reality, the Internal Revenue Code places zero age restrictions on 529 beneficiaries. By enrolling at least half-time at an accredited community college or public university—whether studying viticulture, Spanish literature, architectural history, or digital photography—a retiree can legally transform an accumulated 529 balance into a completely tax-free stipend covering rent, utilities, food, and high-end technology.
The Statutory Foundation: IRC § 529(e)(3)(B) and the Half-Time Mandate
To execute this strategy without running afoul of the IRS, you must understand the exact statutory architecture governing qualified room and board expenses. Under Internal Revenue Code § 529(e)(3)(B)(i), room and board expenditures qualify for tax-free withdrawal under one non-negotiable condition: the student must be enrolled at least half-time at an eligible educational institution.
Here is how the legal framework breaks down:
- Eligible Institutions: The institution must participate in federal financial aid programs under Title IV of the Higher Education Act. Virtually every accredited public community college, state university, and vocational technical college in the United States qualifies.
- The Half-Time Standard: At virtually all semester-based colleges, "full-time" is defined as 12 credit units. That means "at least half-time" requires taking just 6 credit units—typically two standard 3-unit lecture courses per semester.
- Matriculation Requirement: You must be enrolled in an active degree or certificate-granting program. Simply auditing a class for personal leisure or taking informal, non-credit adult education workshops does not qualify for half-time status or room and board distributions.
Taking two classes a week provides a structured, socially rich intellectual pursuit without consuming your entire retirement. More importantly, those six units act as the legal key that unlocks tax-free housing and living distributions.
The Housing Allowance: How Much Can You Legally Deduct?
The most common misconception about off-campus 529 housing is that you can withdraw unlimited sums to lease a luxury penthouse. The IRS anticipated this and established a strict, equitable ceiling in IRC § 529(e)(3)(B)(ii): the qualified distribution for off-campus housing is capped at the official room and board allowance determined by the educational institution in its published federal Cost of Attendance (COA) budget.
Every accredited college publishes an annual COA breakdown for financial aid purposes. For example, a local public community college or state university in California, Washington, or Colorado typically establishes an off-campus room and board allowance between $15,000 and $22,000 per 9-month academic year (averaging roughly $1,600 to $2,400 per month).
As long as your actual, documented living expenses—rent checks, lease commitments, utilities, and grocery bills—equal or exceed the school's published off-campus allowance, you are legally entitled to withdraw that full dollar figure from your 529 plan completely free of federal and state income taxes.
Do not make the mistake of enrolling in just a single 3-unit class. Under federal tax law, taking 3 to 5 units classifies you as less than half-time. While your tuition, books, and required tech remain 100% qualified, room and board drops to $0 qualified. Maintaining that second 3-unit class is what unlocks the entire $18,000+ annual tax-free housing allowance.
The Math: Spending $600 in Tuition to Unlock $20,000 in Tax-Free Renter Living
For retirees who rent, the financial return on investment of this strategy is staggering. Consider the annual cash flow ledger of a renter enrolled half-time at a local public community college:
| Expenditure Category | Typical Cost (9-Month Academic Year) | 529 Tax Status |
|---|---|---|
| Tuition & Campus Fees (6 units × 2 semesters) | $550 – $1,100 | 100% Qualified |
| Off-Campus Rent (COA Allowance) | $16,000 – $20,000 | 100% Qualified |
| Required Textbooks & Course Supplies | $400 – $750 | 100% Qualified |
| Laptop, Monitor, Peripheral Tech & Internet | $1,200 – $1,800 | 100% Qualified |
| Total Tax-Free Renter Distribution | $18,150 – $23,650 | 100% Tax-Free |
In exchange for an out-of-pocket investment of roughly $600 to $1,000 in tuition and fees, the renting retiree unlocks between $18,000 and $23,000 in completely tax-free living distributions. If those funds were instead withdrawn from a Traditional IRA or 401(k), a retiree in the 22% federal plus 6% state bracket would surrender over $5,500 annually to tax authorities.
The Homeowner Caveat: What Qualifies If You Own Your Home?
For the vast majority of retirees at the age where this strategy matters, homeownership—often owning a home completely free and clear—is the dominant reality. According to Federal Reserve and Census Bureau data, roughly 80% of Americans aged 65 and older own their primary residence.
This raises a crucial question: If you own your home, can you still use this strategy?
The answer is yes, but with essential statutory caveats. When you own your residence, the IRS strictly separates capital ownership costs from consumable operating expenses:
- What Does NOT Qualify: You cannot use 529 funds to pay a mortgage (neither principal nor interest), property taxes, homeowner's insurance, or capital repairs (such as a roof replacement). The IRS considers a mortgage payment as debt service and equity accumulation, not a consumable educational expense.
- What DOES Qualify: All consumable utility and food expenses associated with maintaining the student's residence and nourishment remain 100% qualified higher education expenses under "room and board."
Even without a monthly rent payment, an active retiree student can construct a significant "Homeowner Living Stipend" using basic household bills:
| Homeowner Expense Category | Typical Cost (9-Month Academic Year) | IRS Statutory Justification |
|---|---|---|
| Groceries & Food Supplies ("Board") | $4,000 – $5,400 | Direct statutory definition of student board. |
| Electricity, Gas, Water, Sewer & Trash | $2,700 – $4,200 | Consumable utility operating costs of lodging. |
| High-Speed Internet Service | $720 – $1,000 | Explicitly protected under IRC § 529(e)(3)(A)(iii). |
| Course Supplies, Laptop & Tech Refresh | $1,000 – $1,800 | Qualified hardware and required study materials. |
| Tuition & Mandatory Campus Fees | $550 – $1,100 | 100% qualified higher education expense. |
| Total Tax-Free Homeowner Distribution | $8,970 – $13,500 | 100% Tax-Free |
Because this combined homeowner total of roughly $9,000 to $13,500 sits comfortably below the college's published off-campus Cost of Attendance cap ($16,000–$22,000), 100% of these everyday grocery and utility bills are fully sheltered from taxes.
The Oversaving Trap: Right-Sizing Your 529 Glidepath
Understanding the difference between the renter's burn rate (~$20,000/year) and the homeowner's burn rate (~$10,000/year) exposes a major strategic risk: oversaving into your 529 plan.
If you accumulated $150,000 in a 529 plan and own your home, you will find it mathematically challenging to harvest those gains tax-free. If you enroll in a 3-year associate degree or vocational certificate program, you will only consume roughly $30,000 to $36,000 in qualified homeowner expenses. Even if you deploy the SECURE 2.0 Act rollover loophole to sweep $35,000 into a Roth IRA, you could still be left with $80,000 trapped in the account. Liquidating that stranded balance non-qualified subjects the earnings portion to ordinary income tax plus a punitive 10% IRS penalty.
To avoid this trap, use a Glidepath Target Sizing Formula to engineer a clean landing where your 529 balance hits exactly $0:
Here is how the target funding math lands across two realistic retirement profiles:
- The Homeowner Profile (3-Year Certificate Program):
- 3 academic years × $10,500 annual qualified burn (utilities, food, tech, tuition) = $31,500
- SECURE 2.0 Roth IRA rollover sweep = $35,000
- Target 529 Balance = ~$66,500 (landing the account at $0 with zero tax penalties).
- The Renter Profile (4-Year Associate Degree Track):
- 4 academic years × $20,000 annual qualified burn (rent, food, tech, tuition) = $80,000
- SECURE 2.0 Roth IRA rollover sweep = $35,000
- Target 529 Balance = ~$115,000 (landing the account at $0 with zero tax penalties).
By intentionally sizing your 529 balance to your living arrangement and study horizon, you ensure that every single penny of capital gains is harvested with zero tax drag, leaving the $35,000 Roth rollover to mop up any remaining surplus at the end of your studies.
The True Wealth Alpha: Adjusted Gross Income (AGI) Suppression
While avoiding ordinary income taxes on $10,000 to $20,000 of living expenses is substantial, the secondary benefits of this strategy in retirement planning are even more profound: Qualified 529 distributions are completely excluded from Adjusted Gross Income (AGI).
Keeping your reported on-paper income artificially low generates massive downstream financial alpha across two critical retirement phases:
1. Pre-65 Early Retirees: Maximizing ACA Health Insurance Subsidies
If you retire before Medicare eligibility at age 65, buying private healthcare on the Affordable Care Act (ACA) marketplace can cost an older couple $18,000 to $24,000 annually. Premium tax credits are strictly pegged to your Modified AGI. If you fund your living expenses by liquidating $50,000 from a Traditional IRA, your inflated MAGI crushes your subsidy eligibility. By funding your housing, utilities, and groceries out of an AGI-exempt 529 plan, you can report a modest income, capturing silver-tier ACA healthcare with maximum federal subsidies for near-zero net premiums.
2. Post-65 Retirees: Shielding Social Security and Dodging IRMAA Surcharges
For retirees over 65, qualified 529 distributions do not count toward the "provisional income" formula that subjects up to 85% of Social Security benefits to federal taxation. Furthermore, by keeping MAGI low, you avoid the punitive Medicare Income-Related Monthly Adjustment Amount (IRMAA)—the stealth surcharges that can add hundreds of dollars per month to Medicare Part B and Part D premiums for higher-income seniors.
Execution Checklist & Practical Pitfalls to Avoid
To successfully implement the perpetual student retirement strategy, adhere to four essential administrative rules:
- Designate Yourself as Beneficiary: If you funded a 529 years ago for your children and ended up with leftover capital, you do not need to liquidate the account. Under IRC § 529(e)(2), you can execute a tax-free, penalty-free rollover designating yourself as the new account beneficiary.
- Mind the Summer Gap: Room and board is only qualified during academic sessions in which you are enrolled at least half-time. A standard academic year runs roughly September through May (nine months). To cover your summer utilities, groceries, or rent (June through August), you must enroll for half-time units during the summer session (typically 3 units in condensed 6-week terms, or 6 units across the full summer term).
- Keep Rigorous Documentation: Maintain a dedicated audit folder containing your college registration transcripts confirming half-time enrollment, copies of the college’s published Cost of Attendance budget for that academic year, your signed lease or utility statements (electric, gas, water, trash, internet), and grocery receipts. If audited, the IRS requires proof that your actual expenses met or exceeded the allowance claimed. Pro tip: use a single dedicated credit card for all student grocery and utility autopays.
- Take Classes You Genuinely Enjoy: Remember that you cannot simply sign up and disappear. If you fail to attend, professors will drop you for non-attendance, dropping your registered status below half-time and rendering your living distributions taxable and subject to a 10% penalty. Choose fields you are passionate about—foreign languages, culinary arts, studio art, or local history—and treat the classroom as an enriching lifestyle perk.
Comments